Retirement timing
Test whether the planned date remains resilient when circumstances or assumptions change.
A Sat Nav for your finances
Find answers to the questions that matter most. See your trajectory every month. Understand your weak points and take action before it's too late.

The hidden difference
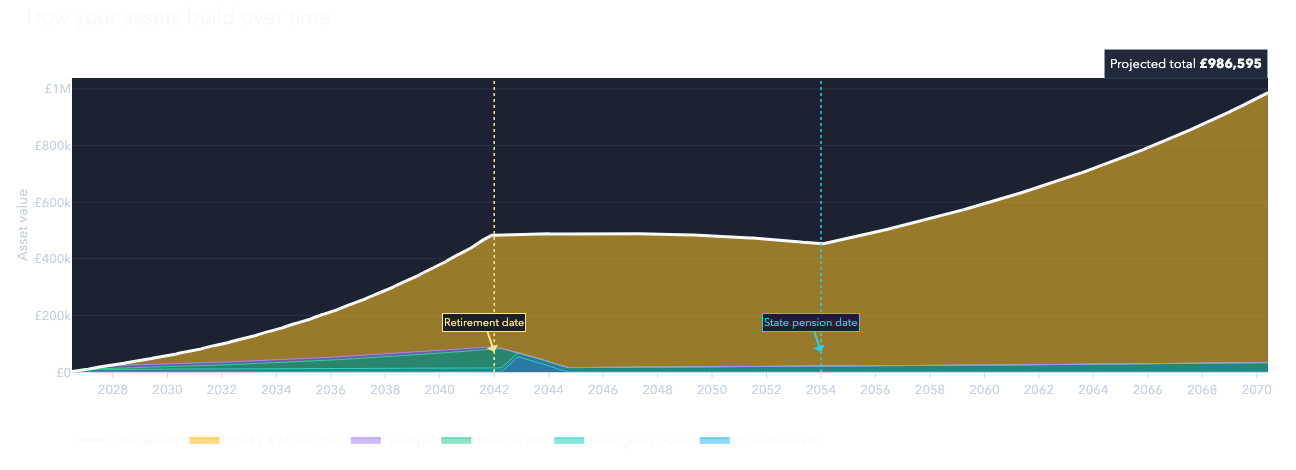
A smooth path from working life to retirement, based on isolated assumptions.
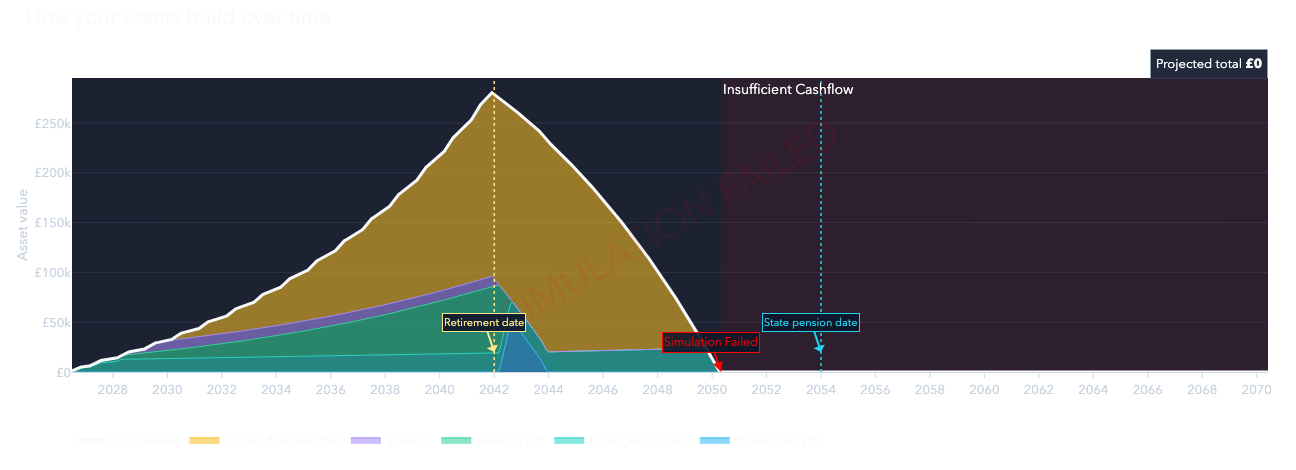
When the actual projection shows they run out of money during retirement.
Cash savings
10% had no cash savings; 21% had under £1,000. [1]
FCA Financial Lives May 2024 survey; UK adults.
Retirement readiness
77% are not expected to reach a moderate standard of retirement. [2]
Pensions UK Retirement Living Standards update; UK working population.
Questula is designed to reveal problems early on and actions to resolve them.
Tackling complexity
Elements such as Income, Taxes, Mortgages, Investments and Pensions are all interconnected. Your outcome depends on all of them.
Increasing pension contributions may reduce tax but also reduce accessible savings.
Repaying a mortgage may reduce future costs but also reduce investment capital.
Retiring earlier changes earnings, pension growth, tax, spending and how long a portfolio must last.
Time matters
Problems revealed twenty years before retirement are likely fixable. The same problems discovered two years before retirement become much more difficult to resolve.
The earlier a problem is visible, the more routes remain available.
Test whether the planned date remains resilient when circumstances or assumptions change.
See the trade-off between pensions, accessible savings, debt and future tax within the same plan.
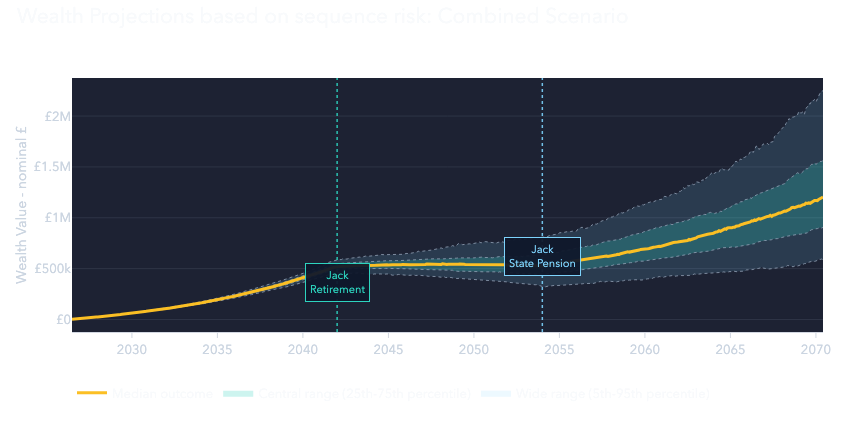
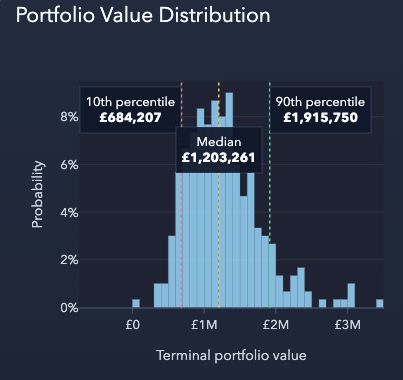
Explore inflation, spending and investment scenarios instead of relying on one smooth forecast.
Evidence-based illustration
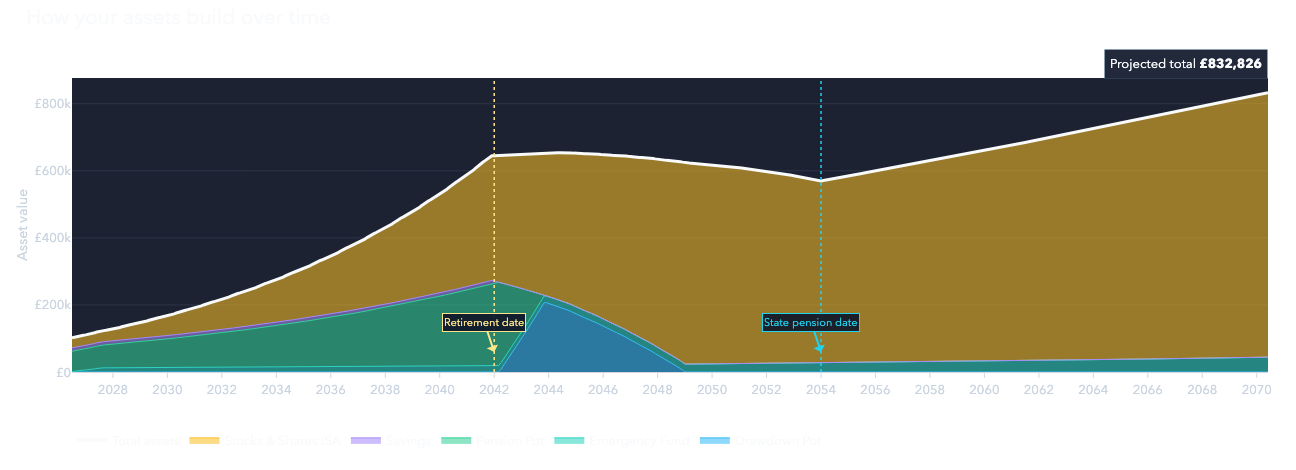
The household below is illustrative, not a statistically ‘average customer’. Published statistics and Questula assumptions are kept separate because UK wealth is highly skewed.
Illustrative Example
Why Questula
The Questula engine wasn’t assembled from generic calculators or AI prompts. It has been designed from the ground up by Dr Amish Poonyth, whose career has focused on using complex system modelling and scenario analysis to support long-term decisions under uncertainty.
Questula also comes from personal experience. Despite a successful analytical career, Amish realised he had many of the same confusing questions that many people face. Thus, Questula was created to bridge that gap by bringing every major aspect of personal finance together into a single financial model.
Your initial calibration session is conducted with Amish
Ongoing value
Questula is not a one-off forecast. It continuously measures, recalibrates and improves your plan as your financial life evolves.
A living financial plan
Your latest financial position is measured against the plan, showing whether you are still on track and what actions—if any—could improve your long-term outcome.
Where you stand in terms of Assets, liabilities, Taxes and Cashflows.
Where current information and assumptions suggest you're likely heading.
What moved materially and which inputs or assumptions contributed.
How to fix the issues with the greatest potential impact.
Questions before you start
Feature comparison
See how Questula's connected planning compares with a typical retirement calculator.
| Capability | Questula | Typical retirement calculator |
|---|---|---|
| Whole-life planning | ||
| Monthly whole-life financial projections | Included | Usually annual |
| Connected cashflow, tax and wealth modelling | Included | Limited |
| Flexible life events and financial goals | Included | Some |
| Flexible growth and economic assumptions | Included | Often included |
| Detailed wealth and cashflow analysis | Included | Varies |
| UK tax and income | ||
| Comprehensive UK income and tax modelling | Included | Basic/varies |
| UK and Scottish tax regimes | Included | Limited |
| Multiple income and investment sources | Included | Some |
| Tax allowances and reliefs | Included | Basic/varies |
| Integrated pension taxation | Included | Limited |
| Pensions and retirement | ||
| DC, DB and State Pension modelling | Included | Often included |
| Flexible retirement and pension access | Included | Some |
| Pension contribution and drawdown modelling | Included | Limited/varies |
| Pension tax and allowance modelling | Included | Limited |
| Retirement income and annuity modelling | Included | Some |
| Savings and investments | ||
| Cash, ISA and investment account modelling | Included | Some |
| Account-level growth and risk assumptions | Included | Often included |
| Multi-asset investment modelling | Included | Some |
| Historical market assumptions | Included | Limited |
| Monte Carlo projections | Included | Some |
| Property and borrowing | ||
| Property purchase, ownership and sale modelling | Included | Limited |
| UK property taxation and transaction costs | Included | Rare |
| Mortgage and overpayment modelling | Included | Limited |
| Loans and consumer debt modelling | Included | Rare |
| Households and inheritance | ||
| Individual and couple planning | Included | Some |
| Connected household cashflow and wealth | Included | Limited |
| Inheritance and estate modelling | Included | Rare |
| Lifetime gifts and wealth transfers | Included | Rare |
| Survivor and beneficiary planning | Included | Rare |
| Scenarios and risk | ||
| Saved and comparable scenarios | Included | Some |
| Historical economic and market data | Included | Limited |
| Investment, inflation and income stress testing | Included | Limited |
| Retirement sequence-risk analysis | Included | Rare |
| Sensitivity and resilience analysis | Included | Rare |
| Ongoing financial monitoring | ||
| Monthly budget and net-worth tracking | Included | Rare |
| Updated whole-life financial projections | Included | Rare |
| Probabilistic financial stress testing | Included | Rare |
| Planning priorities and risk identification | Included | Rare |
| Monthly personal insights report | Included | Rare |
Comparison reflects features commonly available in simple retirement calculators; individual products vary and feature access depends on membership. Outputs are projections, not guarantees or regulated advice.
One connected offer
Build the starting model properly, then measure and recalibrate it throughout your financial life.
Your next step
Build your starting model through a guided session, then monitor your trajectory, test decisions and identify the areas that matter most each month.
See Plans and Pricing